By: Sean Gallagher, CFP®
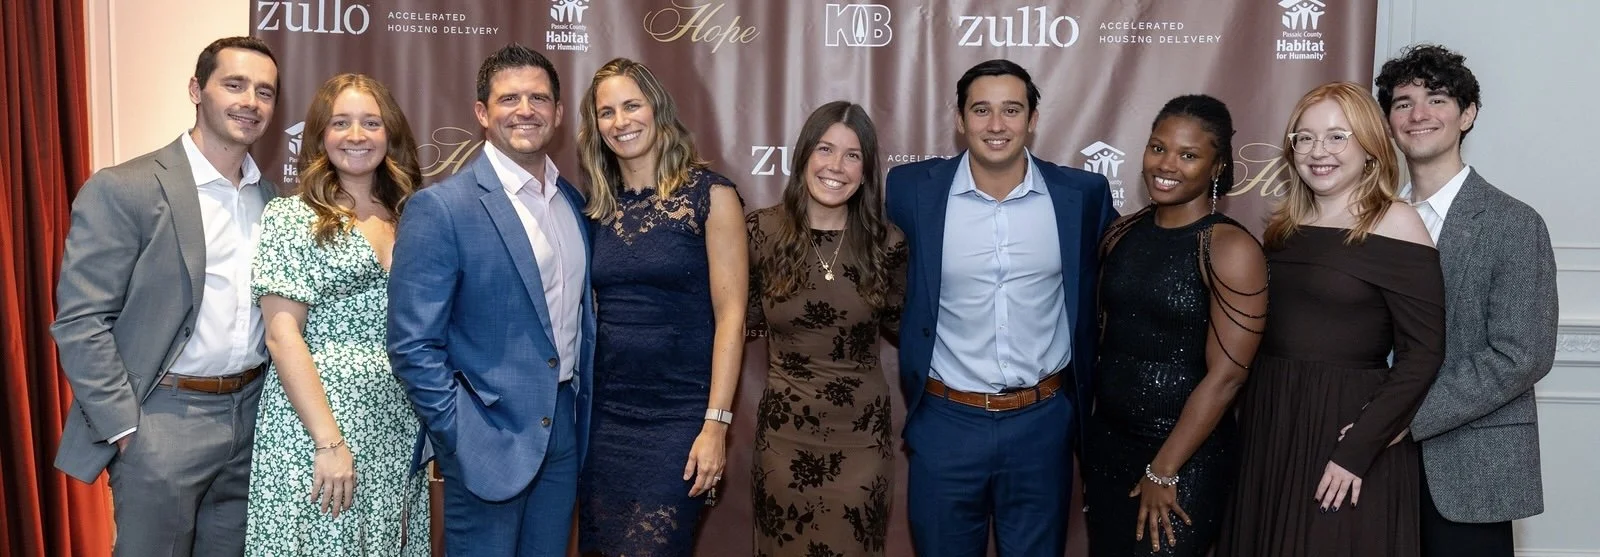
A few weeks ago, I had the privilege of attending the Passaic County Habitat for Humanity Gala. It was inspiring to hear stories from people who have dedicated their time and resources to supporting families throughout Northern New Jersey. What stood out to me most was hearing why people first became involved with the organization. Each person's motivation was different, but they all shared a genuine commitment to helping others.
For some, charitable giving is inspired by a personal experience or a cause close to their hearts. For others, it's about supporting their local community, creating opportunities for future generations, or leaving a lasting legacy.
As financial advisors, we spend much of our time helping clients build and preserve wealth. But an equally important part of financial planning is helping people determine how they want to use that wealth to make a difference.
A little planning can help make those charitable intentions more meaningful.
Start with What Matters Most
Before deciding how much to give or which financial strategy to use, start with a simpler question: What causes are most meaningful to me?
Perhaps you've experienced a family member's illness and want to support medical research. Maybe education played an important role in your success, and you want to create similar opportunities for others. Or perhaps, like those involved with Habitat for Humanity, you feel strongly about strengthening the communities around you.
Once you've identified those priorities, consider how you want to make an impact. Would you prefer to support a handful of organizations consistently, or spread your contributions across several causes? Do you want to see the results of your giving during your lifetime, or create a legacy that continues beyond it?
For additional perspective, our article, “Clarifying Your Charitable Vision,” explores how to identify and define your philanthropic goals.
Make Charitable Giving a Family Tradition
For many of our clients, charitable giving is also an opportunity to bring their families together.
We've worked with many families who want their charitable giving to accomplish two goals: supporting organizations they believe in and teaching their children or grandchildren the importance of generosity.
Imagine a couple who has established an annual charitable giving budget of $20,000. Rather than making all those decisions themselves, they invite their children to participate. Each family member researches an organization, explains why its mission resonates with them, and helps decide how the family's donations will be allocated.
It's a practical way to teach younger generations about generosity and give them a voice in family decisions.
Over time, these discussions may become an annual tradition, creating opportunities to pass down more than financial assets. They help pass down the values that shaped how that wealth was built and used.
Choose the Right Financial Strategy for Your Giving
Once you've determined where you want to make an impact, the next question is how to give effectively.
While writing a check or making an online donation is often the easiest approach, several charitable giving strategies may offer additional financial and tax benefits.
1. Cash Donations
Giving cash directly to a qualified charity is straightforward and allows organizations to put your contribution to work immediately.
Beginning in 2026, taxpayers who take the standard deduction can also deduct up to $1,000 in qualifying cash donations, or $2,000 for married couples filing jointly.
2. Donating Appreciated Investments
If you own stocks or other investments that have increased significantly in value, donating those assets directly to a qualified charity may be more tax-efficient than selling them and donating the proceeds.
For eligible long-term holdings, this approach can generally avoid realizing capital gains and may provide a charitable deduction based on the investment's fair market value, subject to applicable limitations.
3. Donor-Advised Funds (DAFs)
A donor-advised fund can be particularly useful for families looking to organize their philanthropy.
A DAF allows you to contribute assets to a charitable account, potentially receive an immediate tax deduction, and recommend grants to qualified charities over time.
For example, a family could contribute several years' worth of charitable donations in a higher-income year, then distribute those funds gradually to the organizations they support.
DAFs can also provide a structure for involving children and grandchildren in charitable decisions. You can read more about this approach in our article on Donor-Advised Funds and Bunching Charitable Contributions.
4. Qualified Charitable Distributions (QCDs)
For individuals age 70½ or older, a qualified charitable distribution allows money to be transferred directly from an IRA to an eligible charity.
When properly executed, these distributions can be excluded from taxable income and may also satisfy required minimum distributions. This can be especially valuable for retirees who do not itemize deductions.
5. Charitable Giving Through Your Estate Plan
Philanthropy doesn't have to end during your lifetime. Charitable bequests, beneficiary designations, and certain trust arrangements can help support organizations that matter to you long into the future.
Incorporate Philanthropy into Your Financial Plan
Giving intentionally doesn't necessarily mean giving more. Often, it means being more thoughtful about when, how, and where you contribute.
For example, a year with unusually high income, a significant capital gain, or a business sale may present opportunities to accelerate charitable contributions. Meanwhile, retirees may benefit from coordinating IRA distributions with their giving goals.
The tax rules also evolve. Beginning in 2026, taxpayers who itemize can generally deduct charitable contributions only to the extent their total donations exceed 0.5% of their adjusted gross income. This makes it increasingly important to coordinate the timing of charitable gifts with your overall financial plan.
Just as we encourage clients to review their investment, retirement, and estate plans regularly, charitable giving deserves a place in those conversations. Our article, “Building a Year-Round Tax Strategy,” discusses why proactive planning can make such a difference.
A Lasting Impact Beyond Your Wealth
Reflecting on the Habitat for Humanity Gala, what stayed with me most was the sense of purpose behind people's generosity. Everyone had their own reason for getting involved, but they shared a desire to make a difference.
At HIGHLAND Financial Advisors, we believe financial planning is about more than accumulating wealth. It's about using your resources to support the people, organizations, and causes you care about.
The goal isn't simply to give more. It's to make sure your giving reflects what matters most to you.
Sean Gallagher, CFP® is a Partner and Wealth Advisor at HIGHLAND Financial Advisors, a Fee-Only financial planning firm that offers comprehensive financial planning, retirement planning, and investment management. Sean works directly with clients, advising them on their financial planning and investments to help achieve their goals. Sean graduated from Virginia Tech’s financial planning program, successfully passed the CFP® national exam in 2019, and has been with the firm ever since. He is also a member of NAPFA, a professional organization dedicated to serving fee-only advisors.
The foregoing content reflects the opinions of HIGHLAND Financial Advisors, LLC, and is subject to change at any time without notice. Content provided herein is for informational purposes only and should not be used or construed as investment advice or a recommendation regarding the purchase or sale of any security. There is no guarantee that the statements, opinions, or forecasts provided herein will prove to be correct.
Past performance may not be indicative of future results. Indices are not available for direct investment. Any investor who attempts to mimic the performance of an index would incur fees and expenses, which would reduce returns.
Securities investing involves risk, including the potential for loss of principal. There is no assurance that any investment plan or strategy will be successful or that markets will act as they have in the past.
The above article was written with the assistance of artificial intelligence (AI).